Why the Builder's "Sold" Price Next Door Isn't Your Pleasant View Comp
September 24, 2026
September 24, 2026
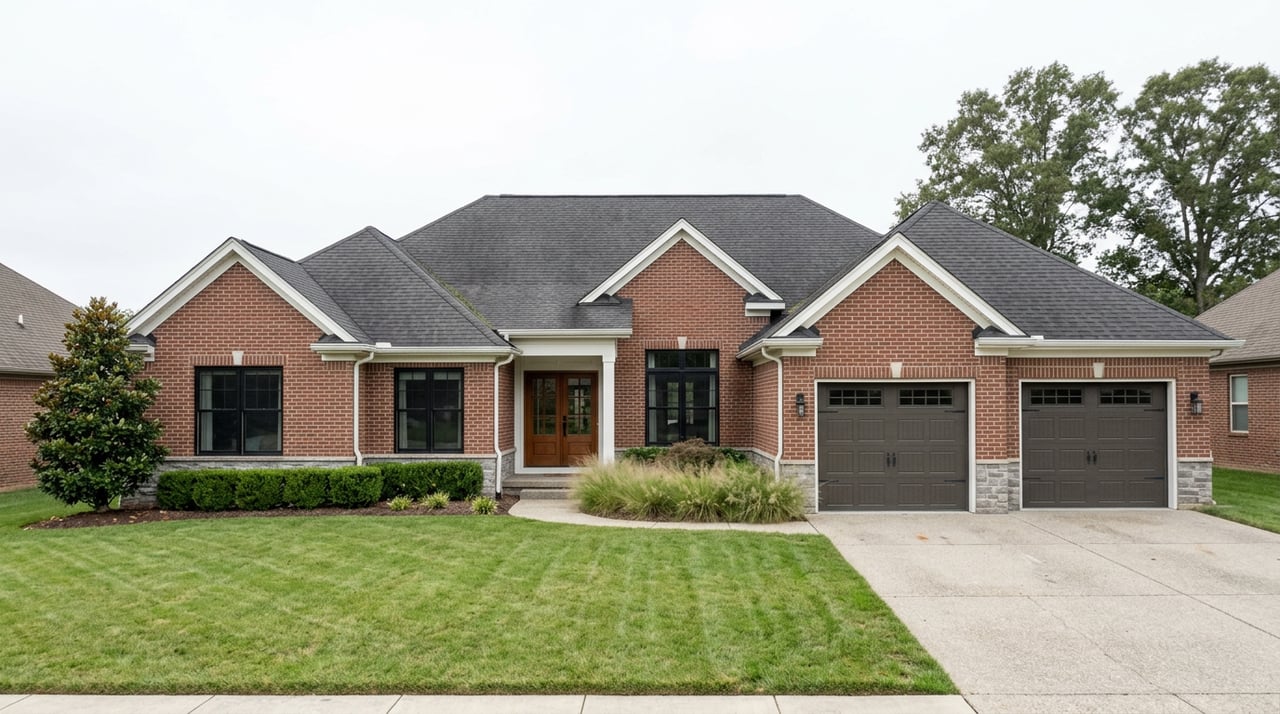
A homeowner getting ready to list a resale house near Bradley Bend pulls up recent sales the way most sellers do first: she looks at what closed nearby in the past few months. A new build a few streets over sold for a number that looks strong. She pencils in something close to it for her own four-bedroom brick ranch, feels good about the plan, and calls it a starting point.
What she doesn't see in that sold price is what the builder gave up to get there.
Ole South, which builds Bradley Bend and Legacy Fields in Pleasant View, lists base prices for Bradley Bend homes between $343,990 and $448,990. Ryan Homes, building at Derby Meadows off Highway 41A, has been advertising a $15,000 credit toward closing costs or an interest rate buydown for buyers who finance through its preferred lender, NVR Mortgage. That $15,000 doesn't show up as a lower sale price in the public record. It shows up as cash back to the buyer at the table, or as a lower effective rate on their loan. The home still closes at the full contract price.
That's not an accident. A builder who cuts $20,000 off a listed price on one lot has just told every future appraiser, every future buyer, and every neighbor who paid full price last quarter that the community's homes are worth $20,000 less. A credit toward closing costs or financing doesn't touch that number. The builder protects the price that becomes the comp for the next ten sales, and gives value through a channel that never gets recorded as a discount.
For a resale seller, this matters because that recorded price is exactly what shows up in a comparative market analysis pulled from the MLS. Unless someone adjusts for what the buyer actually paid net of concessions, a new-construction sale can look like stronger evidence of rising value than it really is.
| Community | Builder | What shows up in the record | What doesn't |
|---|---|---|---|
| Bradley Bend | Ole South | Base prices $343,990 to $448,990 | Whether a given buyer received design credits or financing help |
| Derby Meadows | Ryan Homes | Recorded sale price | A $15,000 closing-cost or rate-buydown credit through NVR Mortgage |
| Eagle's Ridge | Bumpus Builders | Recorded sale price | Buydowns and financing incentives the builder has offered to move inventory, per a News 2 report on the subdivision's early phase |
None of this means a buyer got a bad deal or a builder did anything wrong. It means the number that lands in a spreadsheet doesn't carry the same weight as a resale sale between two private parties negotiating with no incentive to protect anyone else's future price.
Here's the part that actually costs a seller money. When your resale home goes under contract, your buyer's lender orders an independent appraisal. The appraiser pulls closed comps, typically from the past 90 days, and adjusts for differences in size, condition, and lot. If the comps they lean on include a new-construction sale that priced in an unadjusted concession, the appraised value can land below your contract price. When that happens, the buyer either brings extra cash to closing, you renegotiate the price down, or the deal falls apart. None of those outcomes are ones a seller wants to discover for the first time three weeks into a contract.
This is a live risk right now, not a theoretical one. Greater Nashville REALTORS reported 2,928 home closings across the nine-county Middle Tennessee market in August 2026, a 4 percent decrease from the 3,056 closings recorded the same month a year earlier. Regional data for that same month showed roughly 2,365 single-family closings against nearly 2,949 listings that were canceled or expired without selling. When more listings are falling out of contract or expiring than are actually closing, buyers have room to walk away from a deal that doesn't appraise, and sellers have less room to absorb a pricing mistake.
Not every new-construction comp behaves the same way. Highland Reserve is described as a well-established Pleasant View community, and Harris Farms, with its half-acre lots and country views, reads the same way: builder activity there has largely wound down, so recent sales are closer to resale-style, arm's-length transactions. The Enclave, a gated community built around a pond and shared green space, fits a similar pattern once its phases sell out.
Eagle's Ridge is a different story. Bumpus Builders told a local news crew it plans to put up more than 100 homes in that subdivision, which means the community is still in an active build phase with incentives likely to keep showing up as new sections release. A subdivision still selling new inventory is going to keep generating comps shaped by builder financing tools for a while yet. A seller pulling data from an actively building neighborhood needs to weight those sales differently than one from a community where the builder has already moved on.
With more than 90 new-home communities and roughly three dozen builders active across the broader Pleasant View market, ranging from around $199,000 up into the multi-million-dollar range, this isn't a rare edge case. It's the normal texture of pricing a resale home here right now.
The fix isn't complicated, but it does take a closer look at your comps than a quick MLS pull provides.
Ask whoever is preparing your comparative market analysis to separate new-construction sales from resale sales, and to flag which new-construction communities are still actively building versus built out. A sale at Highland Reserve carries different weight than one at Eagle's Ridge this month.
If a new-construction sale is your closest available comp, ask what incentives were advertised at that community around the time it closed. A $15,000 credit on a $400,000 sale is not a small adjustment. Backing it out before you anchor your own price to that number can be the difference between a listing that appraises cleanly and one that doesn't.
Consider structuring your own offer the same way builders do. Instead of cutting your list price to compete, a targeted closing-cost credit can help a qualified buyer get to the table without lowering the number an appraiser sees as your contract price. In Tennessee, remember that property taxes are collected in arrears, so your buyer will actually give you a prorated credit at closing rather than the other way around, and the state's realty transfer tax runs $0.37 per $100 of the sale price. A standard single-family appraisal in Tennessee typically runs $400 to $550. None of these numbers should surprise you on your closing statement if you've planned for them ahead of time.
My house isn't near any of these new-construction communities. Does this still apply to me? It can. When resale inventory is thin in a given pocket of Pleasant View, appraisers sometimes widen their search radius to find enough comps, which can pull in a new-construction sale you wouldn't otherwise expect to compete against.
Can I just ask my agent to only show me resale comps? You can and should ask for that breakdown, but don't ignore new-construction sales entirely. They're part of what buyers are comparing your home against when they tour it, even if they shouldn't be treated as a one-to-one price match.
If I offer my own buyer a concession, will that hurt my appraisal? Not if it's structured correctly. A concession that covers closing costs or a rate buydown, layered on top of a price that's already supported by clean comps, is a very different thing from inflating your price to cover the concession. The first holds up under appraisal. The second usually doesn't.
Pricing a resale home well in a market with this much new-construction activity next door takes more than a glance at recent solds. It takes knowing which of those solds are telling you the truth about value and which are telling you a builder's marketing story. If you're weighing when to list in Pleasant View this fall, Mary Mccooley can walk through your specific comps, adjusted for what actually changed hands, before you put a number on the sign. Start Your Property Search today and get a read on where your home really sits.


Whether you're buying your first home, relocating with the military, or preparing to sell your property, working with Mary McCooley means working with someone who is all in—for you.